Residential Home Appraisals Across Oregon and Washington
Most of the homes we appraise are ordinary homes. A three-bedroom in a Portland neighbourhood,
a subdivision house near Springfield, a condominium, a manufactured home on a few acres.
Appraisal Services of Oregon is a full residential appraisal practice, and the complex work we are
known for sits inside that practice rather than replacing it.
A residential home appraisal is an independent, USPAP-compliant opinion of what a home is worth,
prepared by a state certified appraiser rather than a computer model.
Every property type is
welcome here: single-family homes, subdivision and planned-development properties,
condominiums, townhomes, manufactured homes, and homes on acreage. Homeowners order
appraisals for their own reasons, from pricing a sale to removing PMI to settling an estate, and each
of those purposes shapes the assignment. The fee follows the work the property requires, never a
rate card. Appraisal Services of Oregon appraises the house you actually have.
The fee follows the work the property requires, never a rate card.
Definition
What Is a Residential Home Appraisal?
A residential home appraisal is an independent, documented opinion of a home’s market value,
developed by a licensed appraiser and supported by verified comparable sales. The appraiser
inspects the property, measures it, records its condition and features, researches what similar
homes have actually sold for, adjusts for the differences between those homes and yours, and
reports a value with the reasoning attached.
Every report from this practice is prepared by a State Certified Residential Real Estate Appraiser
licensed in Oregon and Washington, in full compliance with the Uniform Standards of Professional
Appraisal Practice.
Property Types
What Types of Homes Do You Appraise?
Every kind of residential property, from the most ordinary to the most unusual. The list below covers
the great majority of assignments:
Single-family homes
in established neighbourhoods, from starter houses to long-held family homes.
Subdivision and planned-development properties
where the comparable sales are close by and the analysis is straightforward.
Condominiums and townhomes
where the unit, the complex, the association, and the governing documents all enter the analysis.
Manufactured homes
on owned land, including homes many appraisers decline to take.
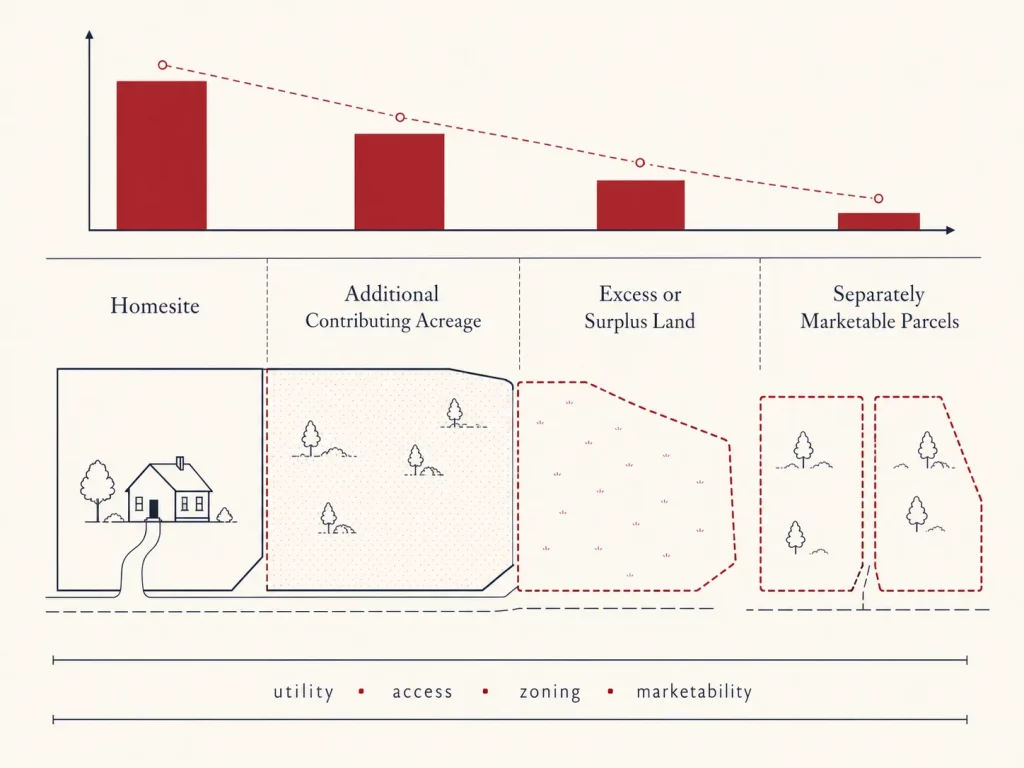
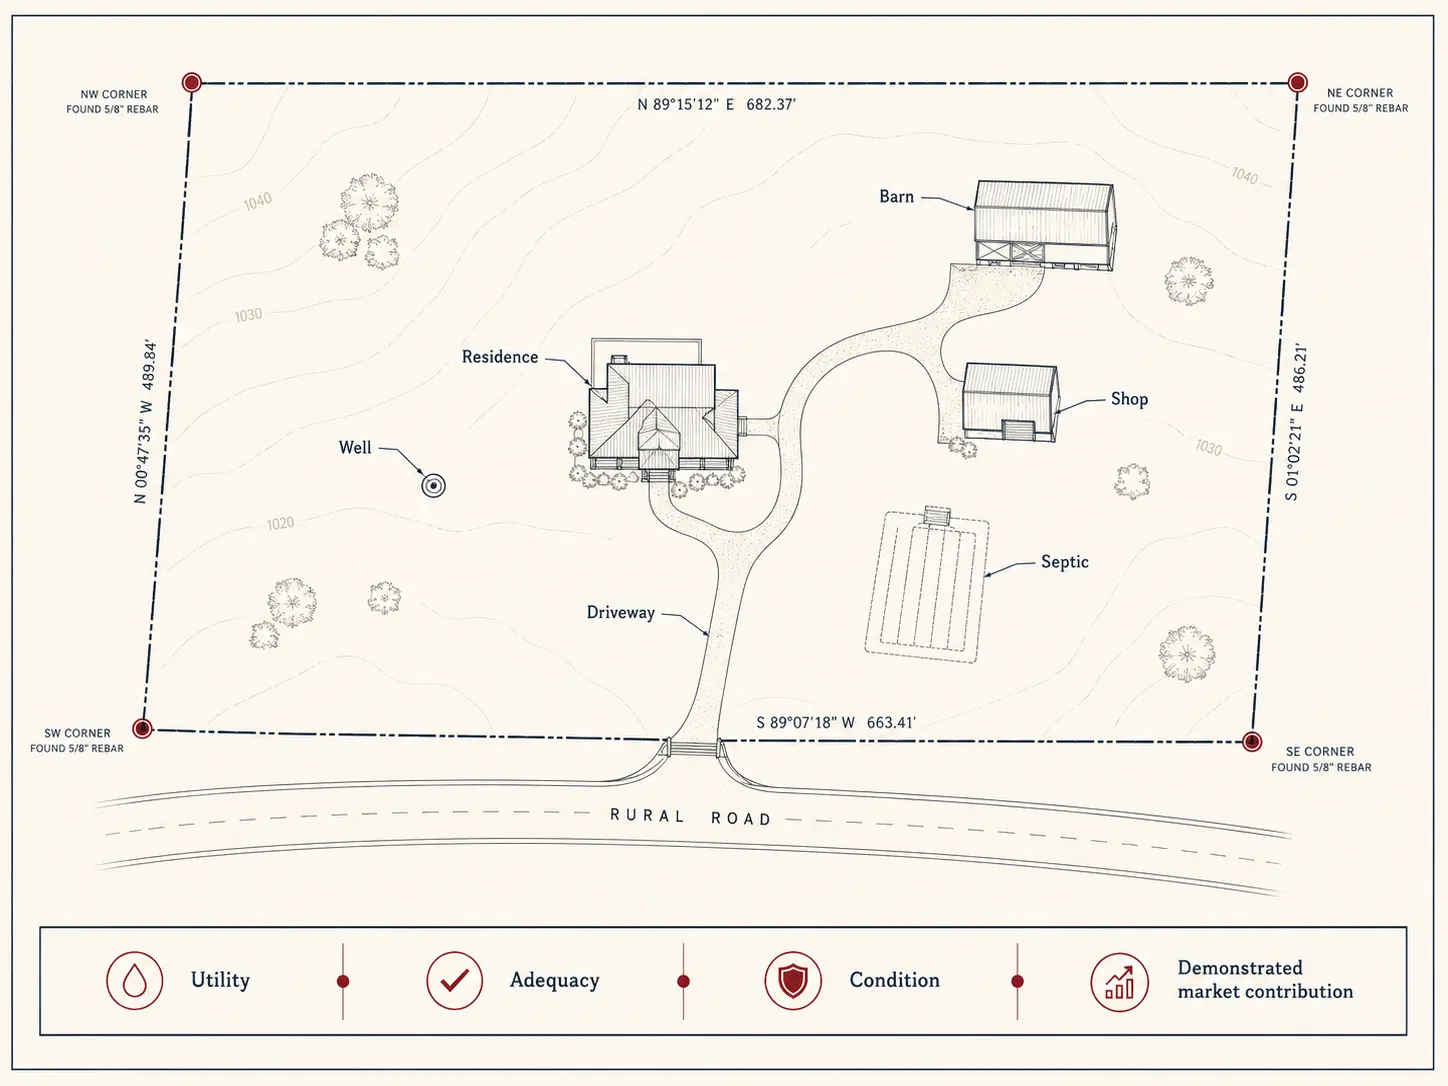
Homes on acreage
where the land, outbuildings, wells, and septic systems each carry value of their own.
A typical and complex residences
properties without a close neighbourhood match anywhere nearby.
If your home is a normal house in a normal neighbourhood, it is exactly the kind of property this practice appraises every week. If it is unusual, it is the kind other appraisers send here.
List price and market value, and where each one comes from
Purposes
Why Homeowners Order a Residential Appraisal
Homeowners order appraisals when a decision depends on knowing what the property is truly worth. The purpose of the assignment shapes how the appraisal is developed, so each situation below has its own page with the detail that applies to it.
01
Before selling
An independent value before the list price is chosen, with no commission interest attached.
Why a State Certified Residential Appraiser Matters
A certified appraiser is accountable to a public standard, and that accountability is what makes the value usable. State certification requires documented education, supervised experience, and examination, and it carries an ongoing obligation to remain independent and impartial on every assignment.
With more than 24 years of residential appraisal experience and over 15,000 properties personally
appraised across Oregon and Washington, this practice brings the same standard to a subdivision
home that it brings to a complex rural assignment. The house is different. The method is not.
home in an established
neighbourhood, ordered by the owners before deciding whether to sell or refinance.
Recent sales on the same street made the comparable analysis straightforward, and the
completed report gave the owners a documented market value they could use for either
decision. Assignments like this one, on ordinary homes in ordinary neighbourhoods,
remain the foundation of the practice.
A separation-date value rebuilt from historical market evidence
The same standard on every assignment
INDEPENDENT VALUE
Residential Appraisal vs an Online Home Estimate
An appraisal is a signed opinion of value from someone who stood in the house. An online estimate
is a model output produced from public records and past sales, and it has never seen the property.
The model does not know the kitchen was remodelled, that the roof is new, that the lot backs onto a
busy road, or that the basement finish was never permitted.
Online estimates are useful for curiosity. When a decision has money, a court, or a tax filing
attached to it, the evidence has to come from someone who is accountable for it.
Who It Serves
Who Uses Residential Appraisal Services?
Homeowners make up most of the work, and they are the reason this practice exists. Three other groups rely on the same reports:
Homeowners
who need an independent value before selling, refinancing, planning, or
settling a family matter.
Real estate agents
who want a third-party value behind a difficult pricing conversation or an
unusual property.
Attorneys, executors, and trustees
who need a value that holds up when it is examined on
a record.
Lenders and financial professionals
who require an independent opinion of value to
support a decision.
Many homeowners contact this practice without knowing which type of appraisal their
situation calls for. A conversation about the property and the reason behind the request
usually settles it in a few minutes, and in some cases the outcome is that no appraisal is
needed at all. Understanding the purpose before the assignment begins is what
produces a report that actually serves the decision behind it.
A separation-date value rebuilt from historical market evidence
How It Works
The Residential Appraisal Process in Three Steps
1
Start with a call
Call 503-757-7100 or send a request with the property details and the reason you need the value. The purpose shapes the assignment, so it is worth a minute of conversation.
2
We inspect and research
One appointment covers the interior, the exterior, the site, and any
outbuildings. The comparable sales research follows.
3
You receive a documented value
A clear, USPAP-compliant report showing the value, the
comparable sales behind it, and the reasoning that connects them.
The Fee
How Much Does a Residential Appraisal Cost?
The cost of a residential appraisal follows the specific assignment rather than a published rate,
because the work varies more than most people expect. A subdivision home with five recent sales
nearby is a different assignment from a manufactured home on twenty acres with no comparable
sale within ten miles. Six factors set the fee:
01
Property type and complexity
02
Intended use of the appraisal
03
Purpose of the assignment
04
Property location and travel requirements
05
Research and analysis required
06
Scope of work and reporting requirements
One brief conversation settles the scope and produces an accurate quote.
Residential Appraisal Coverage Across Oregon and Washington
Appraisal Services of Oregon serves clients across the Portland Metro, the Willamette Valley from
Salem through Eugene-Springfield, the Oregon Coast, the Columbia River Gorge, and Southwest
Washington, with select assignments beyond the primary service area.
5
SERVICE REGIONS
Portland Metro · Willamette Valley · Oregon Coast
Columbia River Gorge · Southwest Washington
Select assignments outside the primary service area
FAQ
Residential Appraisal Questions Homeowners Ask
How long does a residential appraisal take?
The on-site inspection of a typical home usually takes under an hour. The research and analysis behind the report take longer, and the delivery date is confirmed when the inspection is scheduled. Larger properties, acreage, and assignments requiring historical research extend the timeline.
Do I need to be home for the inspection?
No, but someone needs to provide access to the interior, the exterior, and any outbuildings. Many owners are present and use the opportunity to point out improvements that might not be obvious. Others arrange access and leave it to the appraiser.
How should I prepare my home for the appraisal?
No cleaning, staging, or repairs are required. The home is valued in its actual condition, and normal household clutter has no effect on the opinion of value. What helps is access to every room and any documentation of improvements, permits, or recent work
Does the appraiser measure the house?
Yes. The living area is measured directly rather than taken from public records, which are frequently wrong. That measurement is one of the most common reasons an appraised size differs from what a tax record or listing shows.
What is the difference between an appraisal and a home inspection?
An appraisal develops an opinion of value. A home inspection evaluates the condition of systems and components for a buyer’s benefit. The appraiser notes condition as it affects value but does not test the furnace, the wiring, or the roof. The two reports serve different purposes and are not substitutes.
Will my appraisal match my property tax assessment?
Often not, and that is expected. Assessed value is a mass-appraisal figure produced for taxation, updated on a schedule, and calculated without anyone entering the home. An appraisal reflects what the market supports for that specific property on a specific date, based on verified sales.
Can I order an appraisal myself, or does it have to come through a lender?
You can order one directly. Appraisals ordered by a homeowner for their own decisions, such as pricing a sale, settling an estate, or supporting a PMI removal request, are a normal part of this practice. Appraisals used for a mortgage loan are ordered through the lender’s own process.
Do you appraise condominiums and townhomes?
Yes. Condominium and townhome assignments consider the unit itself along with the complex, the association, and the governing documents, since all of those affect what a buyer will pay.
Do you appraise manufactured homes?
Yes. Manufactured homes on owned land are a regular part of the practice, including homes on acreage. These assignments often need broader research, because comparable sales have to reflect both the home and the land component.
How recent do comparable sales need to be?
As recent as the market allows. In an active neighbourhood, sales from the past few months are usually available. In rural areas or for unusual properties, the search widens across a longer period and a larger area, and the report explains the reasoning behind every adjustment made.
What if part of my house was built without permits?
It is analysed rather than ignored. Unpermitted additions and finished spaces are common, and the question is how the market responds to them in that location. The report states what was observed and how it was treated in the analysis.
Can I use one appraisal for more than one purpose?
Every report names its client, its intended users, and its intended use, and it is reliable for the purpose it was prepared for. If more than one purpose is in play, say so at the start, because that shapes how the assignment is set up and can save ordering a second report later.
Do you appraise new construction?
Yes. New construction and recently completed homes are appraised in the same way, using sales of comparable newer properties, with the plans and specifications considered where the work is not yet finished.
How far do you travel?
Across the Portland Metro, the Willamette Valley from Salem through Eugene-Springfield, the Oregon Coast, the Columbia River Gorge, and Southwest Washington. Assignments beyond that area are accepted when the property and the required expertise are a good fit, so it is always worth asking.
Need an appraisal in Oregon or Washington?
Appraisal Services of Oregon serves clients across the Portland Metro, the Willamette Valley from Salem through Eugene-Springfield, the Oregon Coast, the Columbia River Gorge, and Southwest Washington, with select assignments beyond the primary service area. Call or send a request today.